Leave Encashment: Why the Salary Divisor Changes the Result comes down to one part of the daily-rate calculation: the number used to divide the salary base. Keep the salary base, divisor and eligible leave days separate, and it becomes much easier to see why two estimates can show different payouts.
Key Takeaways
| Question | Short answer |
|---|---|
| How does the divisor change the payout? | A lower divisor produces a higher daily rate when the salary base stays the same. |
| Which salary amount should I use? | Use the salary components defined by the applicable terms and rules, not an assumed gross-pay or CTC figure. |
| Can every unused leave day be encashed? | No. The leave policy and local rules determine which leave types and days qualify. |
| How can I check my leave-day figure? | Compare the policy-defined balance with the Leave Balance Calculator, which tracks remaining days and hours. |
| Where can I estimate an India payout? | The Leave Encashment Calculator estimates a payout and tax exemption under Section 10(10AA). |
| Where can I check India tax treatment? | The India leave-encashment tax guide explains the exemption calculation separately from the gross payout. |
What the salary divisor does in a leave-encashment formula
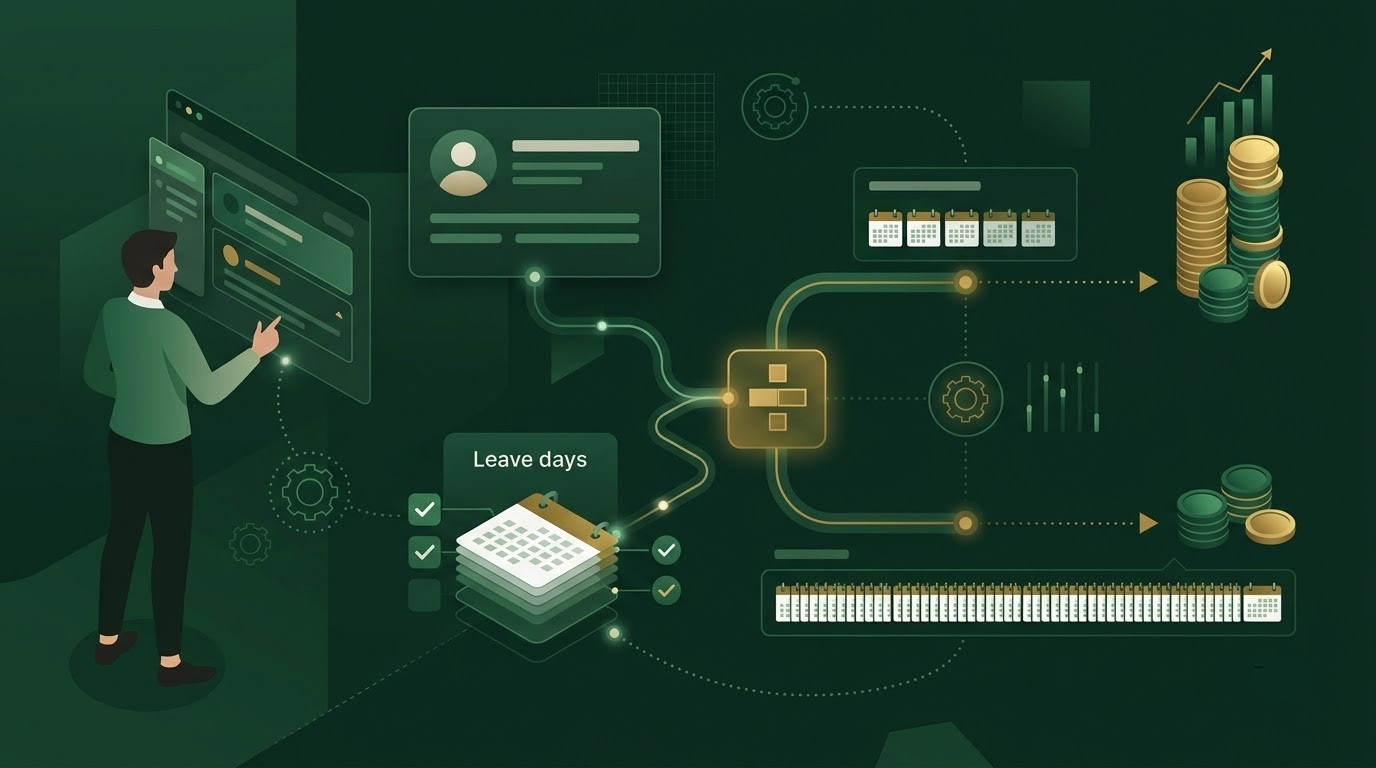
A common leave-encashment formula is eligible unused leave days × daily salary rate. The daily salary rate is often calculated as specified salary base ÷ divisor, so keep the base and divisor separate when checking a result.
The divisor turns a salary amount into a per-day amount. A divisor of 30 treats the salary base as a calendar-month amount spread across 30 days, while a divisor of 26 uses a different calculation convention.
Neither divisor is universal across employers or jurisdictions. The employment terms, leave policy, payroll setup and applicable local rules determine which method governs your payout.
The arithmetic moves in the opposite direction from the divisor: for the same salary base, dividing by 26 produces a higher daily rate than dividing by 30. Multiply that higher rate by the same eligible leave days, and the estimated encashment rises too.
Compare the payout using the same salary and leave balance
Hold the salary base and leave days constant to isolate the divisor’s effect. With a salary base of ₹30,000 and 10 eligible days, a divisor of 30 gives ₹10,000, while a divisor of 26 gives about ₹11,538.
| Calculation | Daily rate | Payout for 10 days |
|---|---|---|
| ₹30,000 ÷ 30 | ₹1,000 | ₹10,000 |
| ₹30,000 ÷ 26 | About ₹1,153.85 | About ₹11,538 |
In this comparison, the divisor alone creates the difference. When comparing payroll results, use the same salary base, eligible leave days and rounding method in both calculations; changing several inputs at once can hide the cause.
The Leave Encashment Calculator is a free estimate for government and private employees in India. It calculates an estimated payout and tax exemption under Section 10(10AA), making it useful for comparing inputs and checking how a result changes when the working-days-per-month basis changes.
Use any online estimate as a calculation aid, not proof that a specific divisor applies to your employment. The policy and local rules determine the method, and an estimate cannot replace that governing basis.
Did You Know?
An employee entitled to two weeks (10 work days) annual vacation who works full-time, eight hours per day and 40 hours per week will earn 1.538 hours of paid vacation for each week worked at least one full day.
Source: California Department of Industrial Relations, Division of Labor Standards Enforcement
Separate salary components from the divisor
The salary base may mean basic salary alone, or basic salary plus dearness allowance, depending on the applicable terms and rules. Gross pay and CTC are not automatically the base for leave encashment.
Think of the calculation as two separate decisions: which salary components go into the numerator, and which divisor converts that amount into a daily rate. Changing basic salary or including dearness allowance changes the numerator; changing the divisor changes the conversion.
If pay components changed during the relevant period, identify the rate and effective date the applicable formula uses. Do not combine an old basic salary with a newer allowance figure unless the governing formula supports that approach.
For an India-focused tax estimate, the salary definition used for an exemption calculation may have its own rules and reference period. That is a separate question from which salary base and divisor produce the gross encashment amount.
Keep the gross payout and any tax-exempt amount distinct. The exemption rules affect the taxable portion, not the underlying multiplication of eligible leave days by the daily salary rate.
Check which leave days qualify for encashment
A leave balance is not automatically a payable balance. The policy may allow encashment of earned or annual leave while treating casual, sick or other leave differently.
Check the policy for eligible leave categories, any maximum balance that can be paid out, and the specific day count used in the formula. The calculation may rely on accrued days, the credited balance at a defined date, or another policy-defined figure.
Partial months and changing balances need the organization’s stated accrual and rounding method. For example, a policy may define how it counts a partial pay period; applying a different accrual or rounding approach can change the eligible day count before the divisor even enters the calculation.
The free Leave Balance Calculator helps track leave balances and calculate remaining days and hours, utilization rate, and, in accrual mode, a next-accrual countdown and projected year-end balance. It is useful for reconciling the number of days you believe are available with the balance the employer’s policy makes eligible for payout.
An employee quitting August 7, 2002, with no vacation taken that year or prior carry-over, was owed $936.00.
Source: California Department of Industrial Relations, Division of Labor Standards Enforcement
This is a California vacation-pay example, not a universal leave-encashment formula. It illustrates why the eligible balance and the rules for a particular jurisdiction matter alongside the salary divisor.
Find the applicable divisor and resolve conflicting guidance
Start with your employment agreement and leave policy. Compare their wording with the payroll configuration and applicable local rules, because a generic formula can show the arithmetic but cannot establish which divisor your employer must use.
Calculation conventions vary by jurisdiction. Keep India-specific labour-code and tax guidance separate from rules that apply in another country; a convention used in one place does not automatically govern a different payroll.
Check whether the payroll setup uses a calendar-month basis, a specified working-days basis or another stated method. A salary slip may show the encashment earning and deduction, but the underlying per-day basis may sit in the policy or payroll configuration instead.
If the documents and payroll result do not match, ask HR or payroll for the calculation in writing. Request each of these inputs:
- The salary components and salary amount used as the base
- The divisor and the rule or policy clause that supports it
- The leave category and number of days treated as eligible
- The accrual, balance-cap and rounding methods used
- Any payroll deductions applied after calculating the gross amount
That breakdown makes it possible to pinpoint whether the difference comes from the salary base, divisor, leave balance or rounding. If the written explanation still conflicts with the employment terms or local requirements, seek qualified local advice.
Did You Know?
An employee who quits on August 7, 2002, without having taken any vacation in 2002, having no vacation carry-over from prior years, and whose final rate of pay is $13.00 per hour, would be entitled to $936.00 vacation pay upon separation.
Source: California Department of Industrial Relations, Division of Labor Standards Enforcement
Understand when encashment is paid and how tax is handled
Leave encashment may be paid while employment continues or when employment ends. The policy and applicable rules determine eligibility and timing, so the same leave balance can be handled differently in different circumstances.
An employer may include the payment in regular payroll or process it separately. In either case, separate the gross encashment from deductions and the net amount received; a lower deposit does not by itself show that the daily-rate formula was wrong.
Tax treatment depends on jurisdiction and payment circumstances. For an India-focused estimate, assess any applicable Section 10(10AA) exemption separately from the gross payout calculation.
When reviewing a payment, compare the gross figure with the stated salary base, divisor and eligible days first. Then check the payslip or separate payment statement for tax withholding and other deductions.
Conclusion
Leave Encashment: Why the Salary Divisor Changes the Result is straightforward once you separate the inputs. The salary base determines what amount is divided, the divisor determines the daily rate, and eligible unused leave days determine how many daily rates are paid.
Use the same inputs to compare estimates, then verify the governing method in your employment terms, leave policy, payroll setup and local rules. Every number counts, but only the applicable formula tells you which one belongs in the calculation.
Frequently Asked Questions
What are the new rules for leave encashment?
There is no single universal rule: the applicable requirements depend on the jurisdiction, employment terms and circumstances of payment. A rule change in one country or employment category does not automatically change another employee’s entitlement.
Is leave encashment part of salary?
It is generally a payment arising from eligible unused leave, but its treatment for payroll, tax or other purposes depends on the applicable rules. A payslip may show it as a separate earning even when the employer processes it through payroll.
Can leave encashment affect notice pay or a final settlement?
It may be included in the overall settlement calculation, but the treatment depends on employment terms and local rules. Review the leave payout as a separate line from notice pay so one amount does not obscure the other.
What should I do if my payroll calculation differs from my estimate?
Compare the salary base, divisor, eligible leave days and rounding method, then request the written calculation basis from HR or payroll. Ask for the gross amount and any deductions to be shown separately so you can identify whether the difference is in the formula or the net payment.
Does rounding the daily rate before multiplying change the payout?
It can, especially when the daily rate has repeating decimals. Apply the rounding sequence specified by the employer’s formula, and use that same sequence for every comparison rather than rounding one estimate earlier than another.
Where can I find the divisor used in my leave-encashment calculation?
Look for a stated per-day formula in the leave policy, employment terms or payroll calculation notes. If the divisor does not appear on the salary slip, ask payroll to identify the configuration or policy wording used to produce the daily rate.
How do I calculate my salary for leave encashment?
Use the salary base specified by the applicable formula, then divide it by that formula’s divisor.
How do I calculate my leave encashment?
Confirm the eligible leave-day count and daily rate under the applicable terms, then multiply them.